Relocation guide
São Tomé & Príncipe:
relocation, cities, cost of living and immigration context in 2026
A country guide covering daily life and cities, population and religion, average salary and costs, relocation appeal and a concise immigration snapshot.
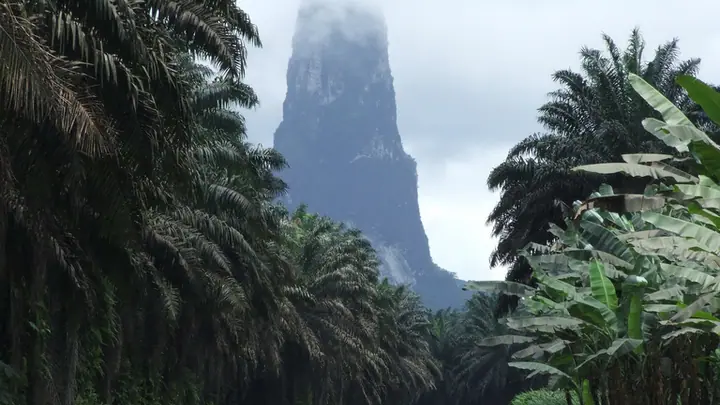
Relocation profile
Key relocation profile
5 facts about the country
Economy and everyday budget
São Tomé & Príncipe sits in Africa; relocants commonly compare bases such as Sao Tome, Trindade. Population is 245K, with day-to-day payments in São Tomé & Príncipe Dobra (STN). The one-person living-cost benchmark is $1,011 per month versus an average after-tax salary benchmark of $271, a useful signal for rent affordability and imported-goods exposure. Immigration context: Investment / Naturalization.
Climate: months, seasons and temperatures
December–February: 23…31 °C · March–May: 24…32 °C · June–August: 23…32 °C · September–November: 23…31 °C. Seasonality is driven mainly by rainfall: wet and dry months matter more than temperature swings; islands also need a separate tropical-storm check. Daily adaptation depends on language, neighbourhood and whether life runs through local rather than tourist services. Before a long lease, test peak-hour transport, private healthcare, schools, banking, internet quality and real government-service lead times.
Personal, business and foreign-asset taxes
Personal income tax: 25%. Standard corporate income tax: 25%. A tax resident generally reports worldwide income, while a non-resident is taxed on local-source income. Residence turns on local day-count and/or centre-of-vital-interests tests. Foreign assets are not usually subject to a separate annual tax merely because they are owned, but their income, dividends, rent and gains can enter a resident's worldwide taxable income; disclosure and CFC rules are separate.
Social and economic figures are comparable 2026 orientation benchmarks. They are useful for country comparison but do not replace a personal budget, tax calculation or city-level verification.
Legacy Partners
Need to test this route against your circumstances?
We can review eligibility, documents, timing and risks before you start the filing process.
Get a consultation